
November 2026
Views from 50 top asset managers across 73 assets, based on 1,400+ individual views.
Look at all 100+ Buy Side Sentiment Tracker charts in the Sentiment Toolbox section of the website.
Main Takeaways
1) Sentiment is Bullish, but not in all ways
Risk appetite remains elevated, but the recent market weakness has taken some of the froth out of buy-side sentiment.
Equities remain the most popular major asset class and Cash the least popular. But November also brought upgrades to Cash, downgrades to Equities and a narrowing gap between sentiment on risky and safe assets.
At the same time, High Yield was upgraded, Industrials remain the most popular equity sector and the broader sector pattern continues to favour cyclicals over defensives.
The bottom line is that the Buy Side remains bullish, but a look beneath the headline numbers reveals too many caveats to describe sentiment as extremely bullish.
2) Maximum Contrarian
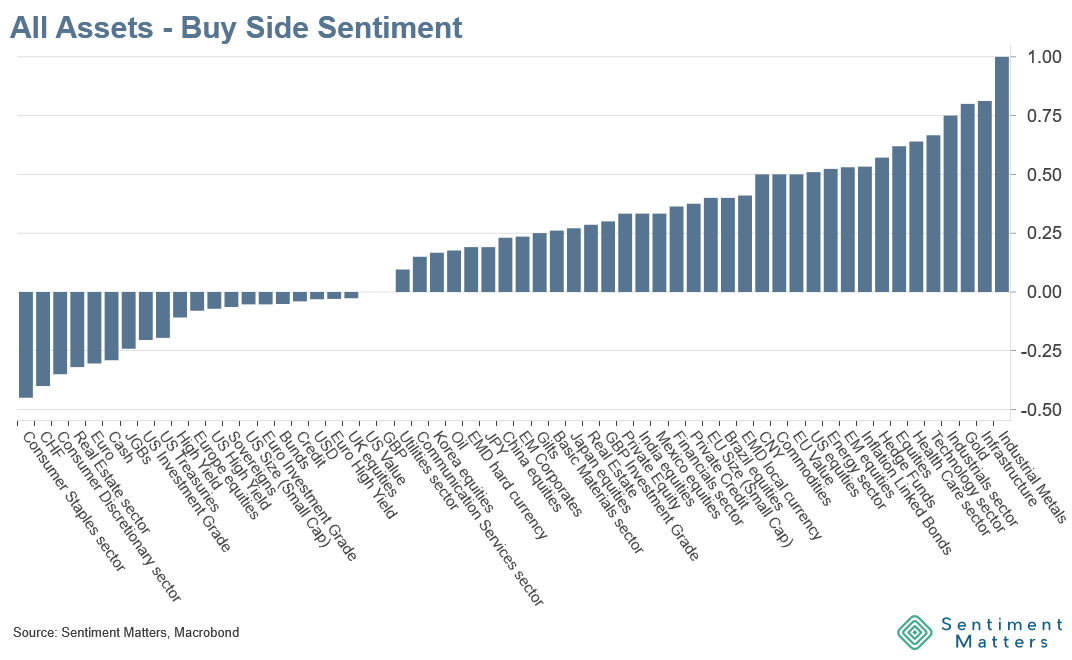
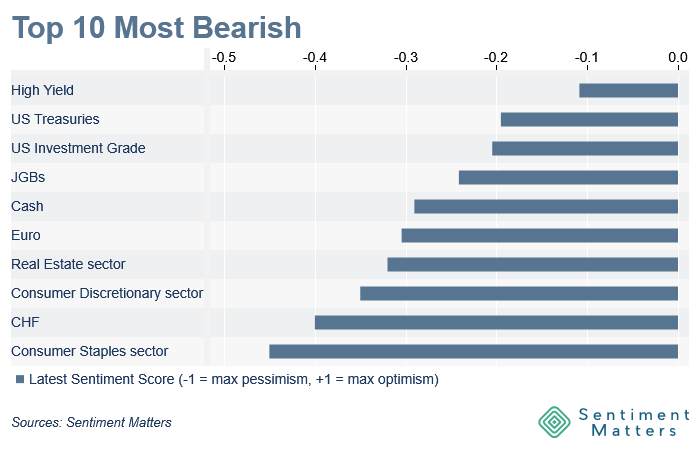
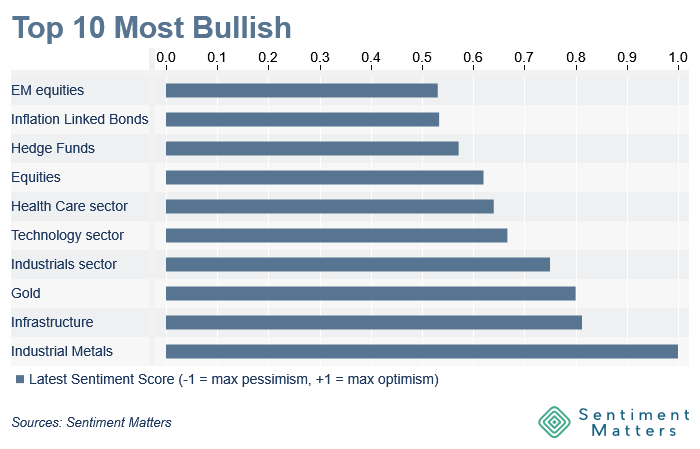
The Buy Side is most bullish on Infrastructure, Industrial Metals and Gold, and most bearish on the Swiss Franc, Cash and Consumer Staples.
Some of these extremes are becoming increasingly interesting from a contrarian perspective.
Copper stands out with universal bullishness. All 13 asset managers expressing a view are bullish. Meanwhile, Gold has seen three consecutive months of upgrades, taking sentiment back to +80% net bullish.
At the other end, Euro sentiment is approaching historical bearish extremes, while European equity sentiment remains deeply unpopular.
As always, extreme sentiment is not a timing signal in itself. But it highlights where expectations are particularly one-sided and where markets may become increasingly vulnerable to surprises.
3) European Downgrades Everywhere
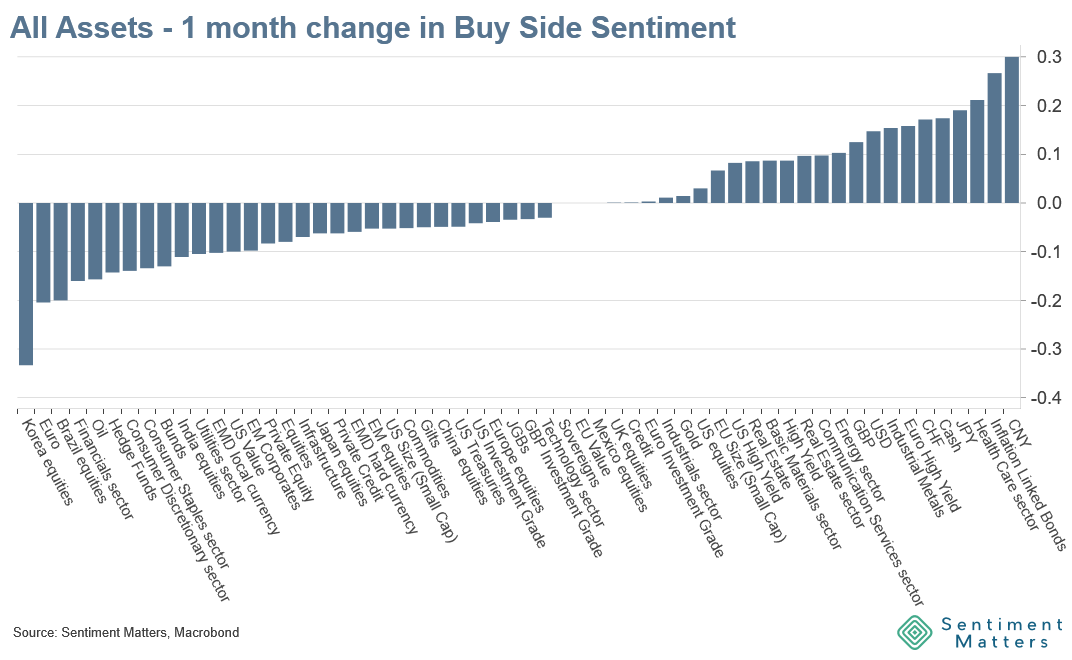
November brought another round of downgrades to European assets.
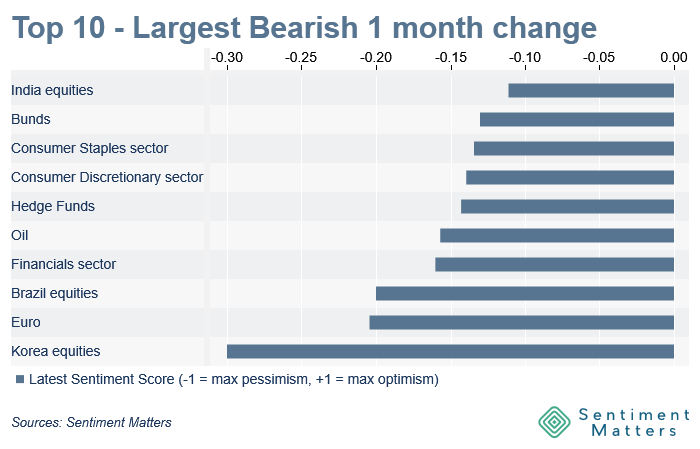
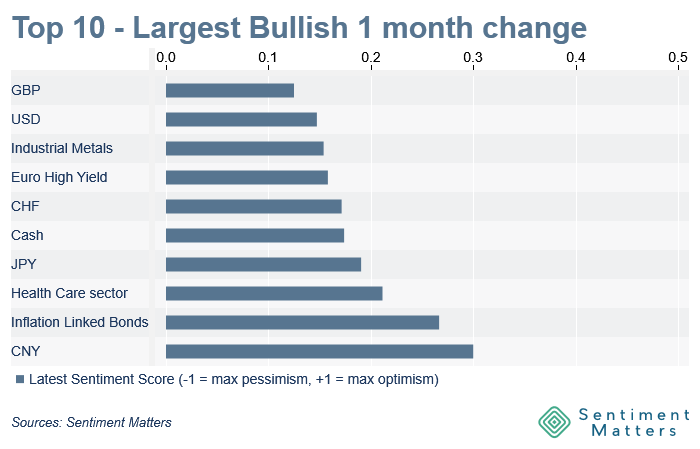
European equities resumed their downward trend, the Euro was the most downgraded asset in the Tracker, and Bunds saw the largest downgrades among sovereign bonds.
These are not isolated developments. They extend trends that have been in place for some time, with political uncertainty seemingly reinforcing an already negative view of European assets.
The contrast with the US is striking. US equities were the only equity region to receive net upgrades, while the US dollar continued its recovery in sentiment.
The US exceptionalism narrative is clearly alive and well. But the gap between US and European equity sentiment has not yet reached the extremes seen immediately after the 2024 US election.
Sentiment
A risk-off shift, but the Buy Side remains fundamentally bullish
A decline in sentiment was to be expected given the weakness in risky assets over the past few weeks.
And November did bring a shift towards risk-off. Three of our five Risk-on/Risk-off indicators declined, while two increased.
But the shift has been relatively small. Some froth may have been eliminated, but buy-side views and positions remain net bullish. Across our indicators, sentiment is also still more bullish than the two-year average.
There are nevertheless some clear signs of increasing caution.