
October 2026
Views from more than 50 top asset managers across 73 assets, based on 1,400+ individual views.
We have added another four asset managers to the Tracker this month as we continue to widen the scope of both the assets and asset managers covered.
Look at all 100+ Buy Side Sentiment Tracker charts in the Sentiment Toolbox section of the website.
Main takeaways
1) Sentiment is bullish, but not in all ways
- Risk appetite is high and rising.
- But a look beneath the headline numbers reveals too many caveats to describe the Buy Side as extremely bullish.
2) Max contrarian
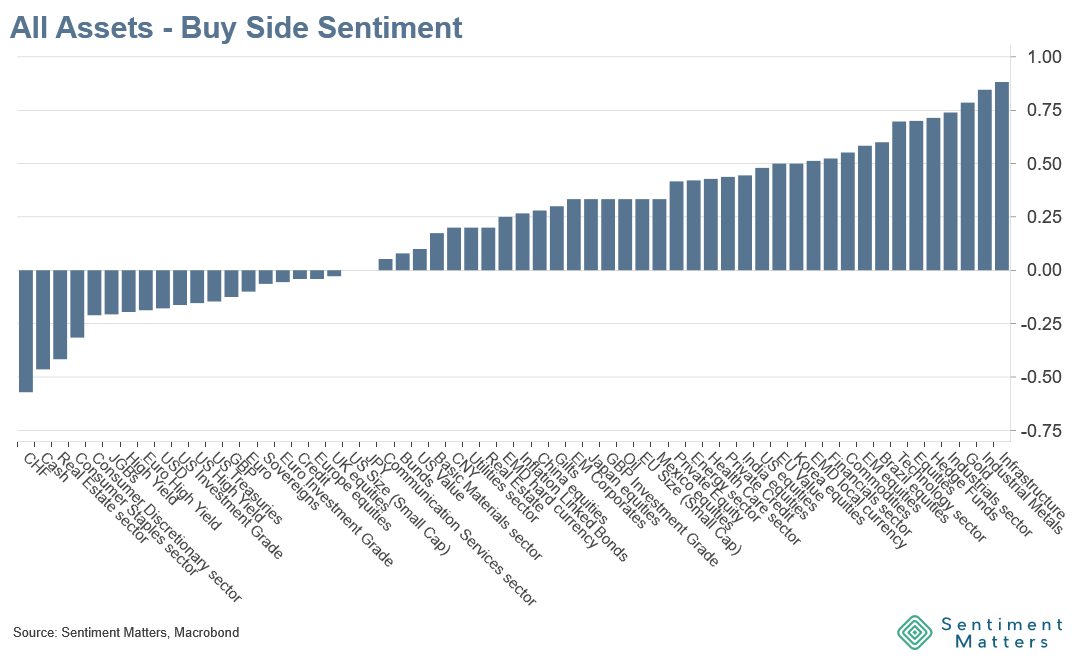
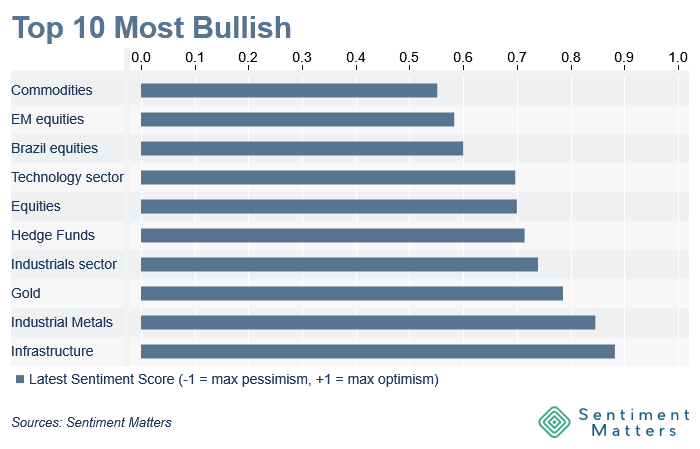
- The Buy Side is most bullish on Infrastructure, Industrial Metals and Gold.
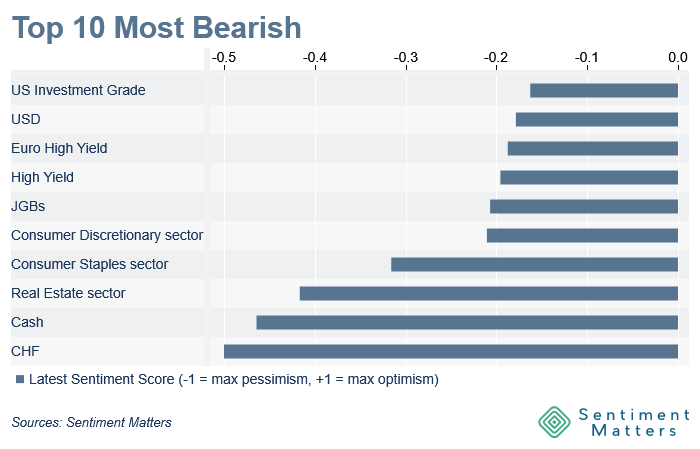
- It is most bearish on the Swiss Franc, Cash and Consumer Staples.
3) Sovereigns — less bearishness than you might think
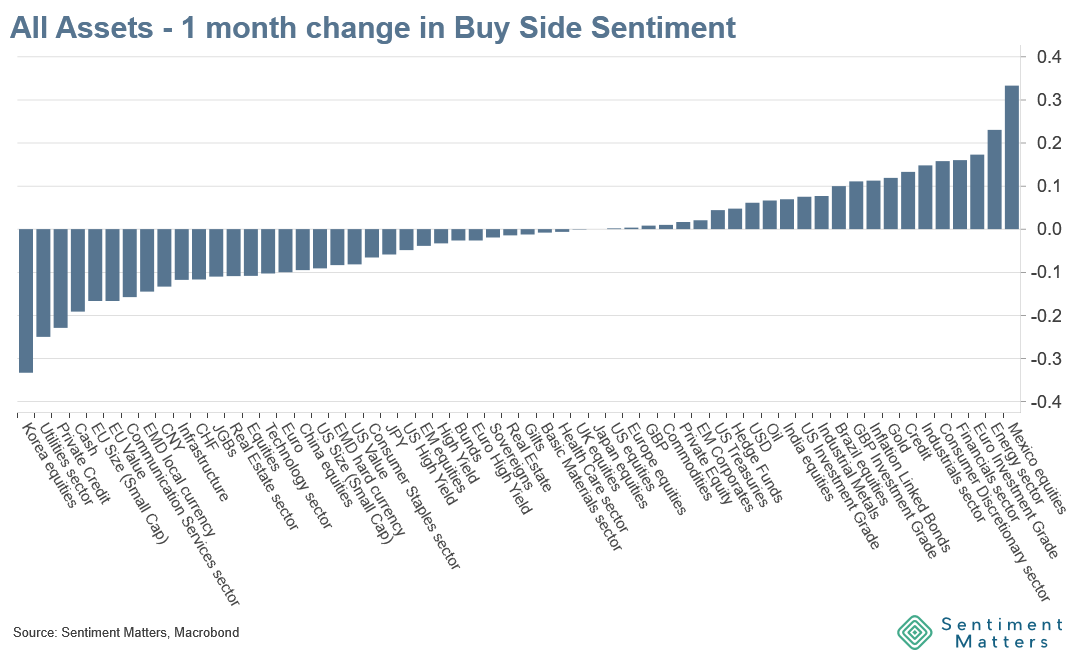
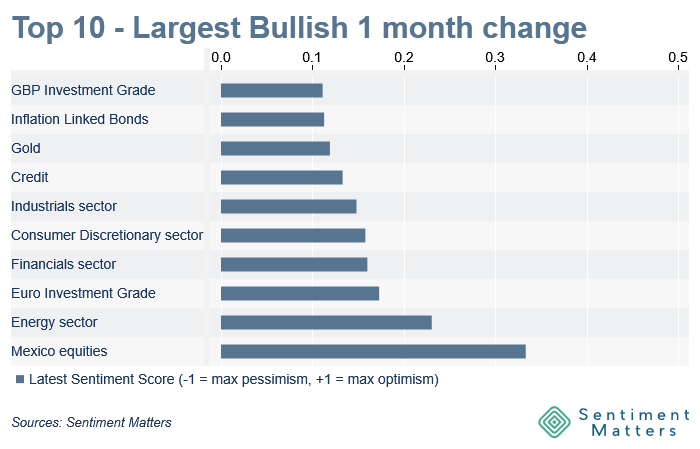
- Sovereigns saw a small net downgrade this month.
- But there are still only slightly more Bears than Bulls, and views are considerably more positive than they were in the spring.
- Treasuries have now been upgraded for four consecutive months.
Sentiment - The Big Picture
Investors are bullish, but...
In many ways, the Buy Side continues to become gradually more bullish.
But beneath the surface, the story is more complicated. This is far from a universally bullish picture.
Let’s start with the evidence pointing towards increasingly bullish sentiment.
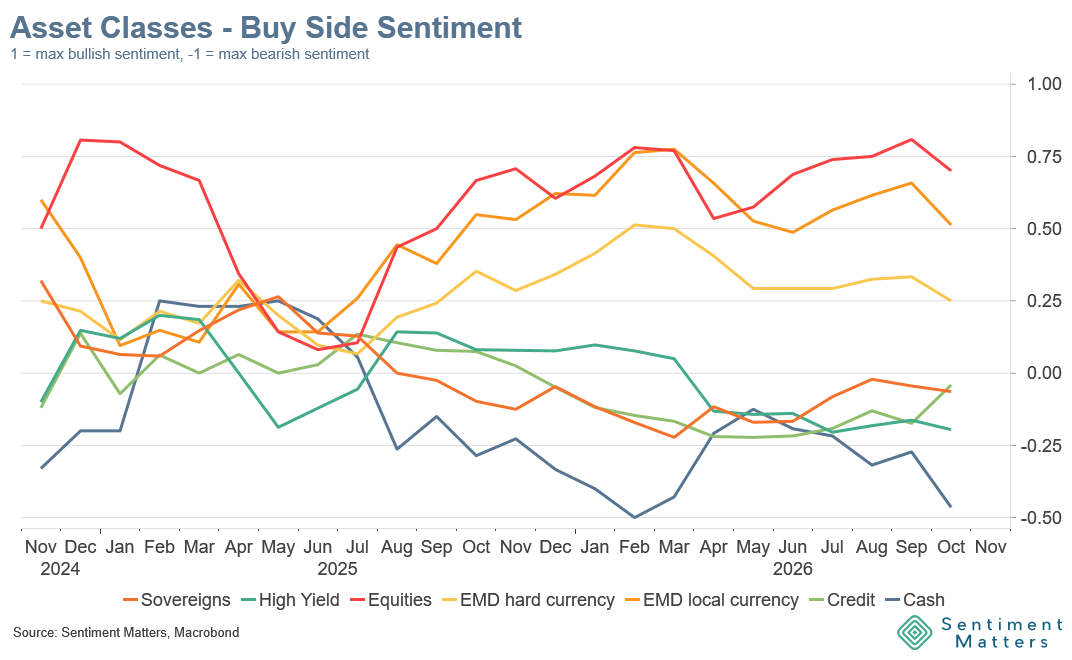
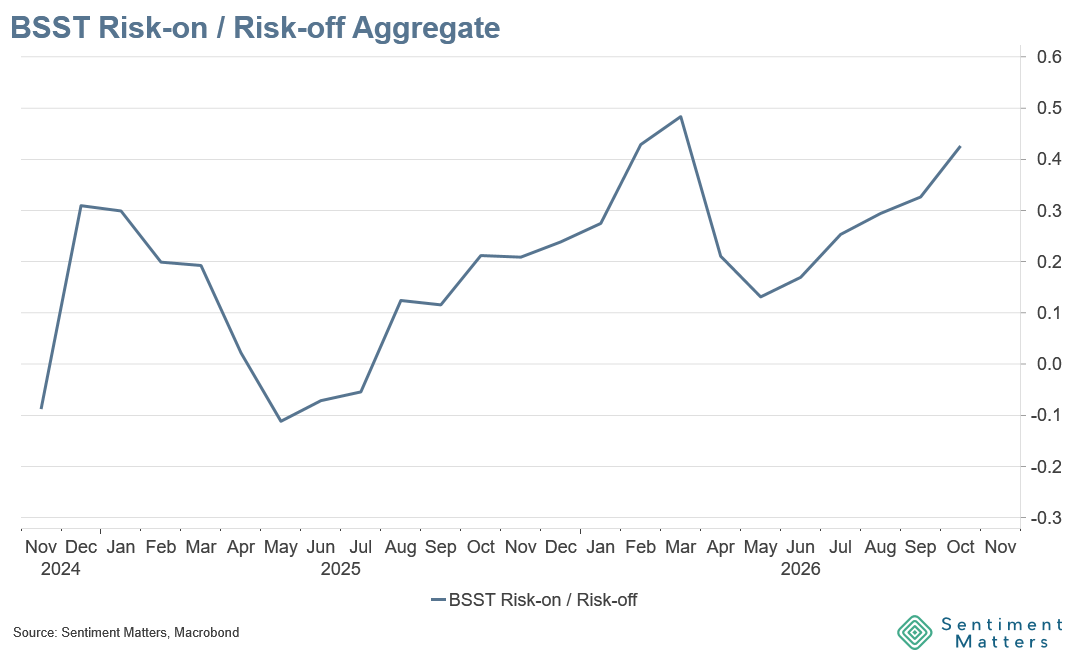
Four of our five Risk-On/Risk-Off indicators increased this month, taking the aggregate to the third-highest level in the history of the Tracker.
It is now only slightly below the peak reached just before the war with Iran earlier this year.
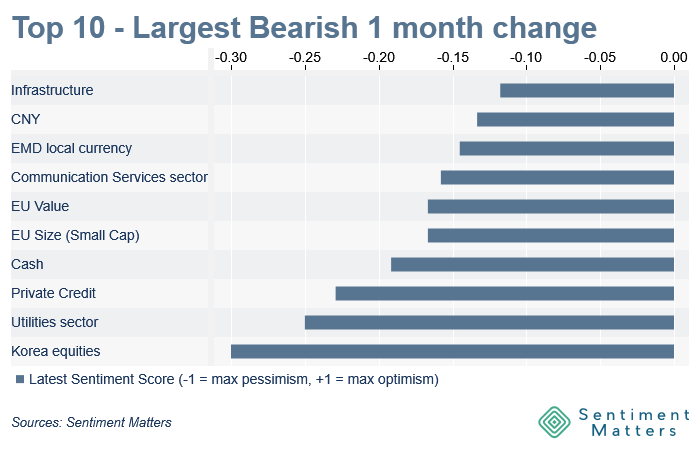
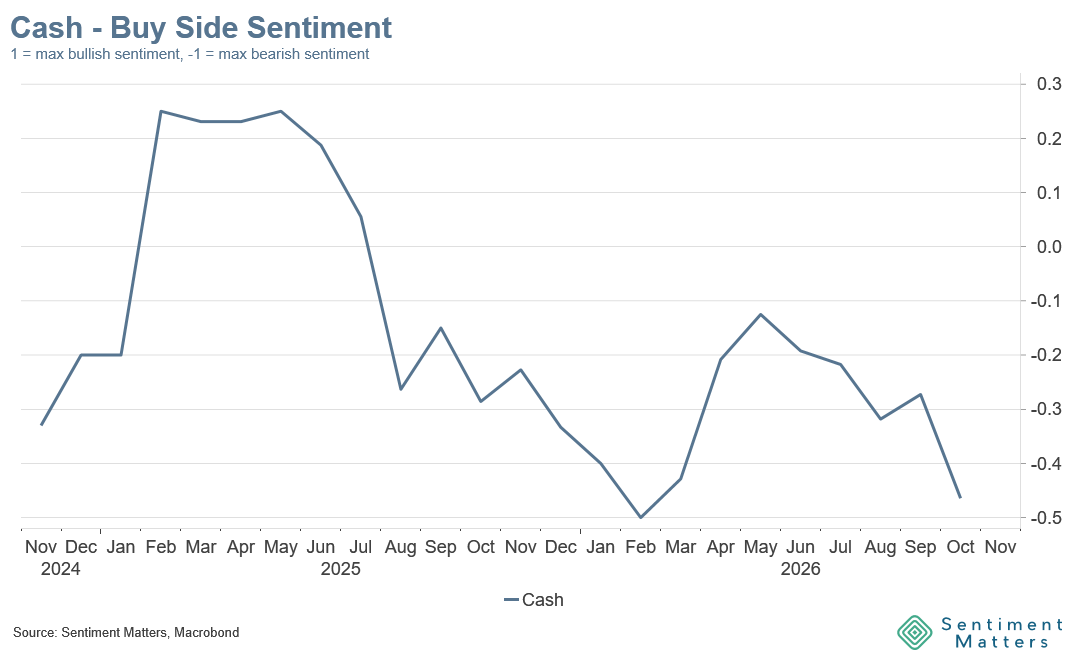
Cash allocations also fell sharply.
At -46% net bearish, Cash was one of the most downgraded asset classes this month and is now the second-most unpopular asset class in the Tracker.
Cash sentiment was only marginally more bearish at the sentiment peak just before the war.
The sector pattern tells a similar story.
The rankings are increasingly dominated by high-beta sectors such as Tech and cyclical sectors that tend to benefit from stronger economic growth.
At the same time, Defensives have been downgraded and, relative to their cyclical peers, are close to Tracker lows in popularity.
Equities remain the most popular major asset class.
At +70% net bullish, they rank sixth across all 73 assets we track.
But not everything fits the increasingly bullish narrative.
Equities actually saw net downgrades this month.
Last month, sentiment stood at +81% net bullish. That has fallen to +70%, following several moves from overweight to neutral and one all the way to underweight.
37 Bulls | 11 Neutrals | 2 Bears
Sovereigns, meanwhile, saw more upgrades than downgrades.
That is striking against the backdrop of poor bond returns and suggests considerably less bearishness than the prevailing narrative might imply.
But it is also not what you would normally expect in a universally bullish environment where investors are shifting allocations aggressively towards risk.
So the absolute level of risk appetite is high — and arguably still rising.
But look beyond the headline numbers and there are too many caveats to describe the Buy Side as extremely bullish.
Equity Regions
Big picture: EM over DM; US still leads Developed Markets
Regional equity views were relatively stable this month.
The preference for Emerging over Developed Markets remains firmly in place and has now persisted for more than a year.
EM equities moved from net bearish throughout much of 2025 to strongly bullish, and sentiment has remained remarkably stable at elevated levels throughout this year.
Within Developed Markets, the ranking remains: